Speed Up Your Personal Loan With Employment Verification
Loan approval speed depends heavily on how quickly you can verify your employment and income. When lenders assess your personal loan application, they need proof that you earn enough to repay borrowed funds.

Flexible Repayment Options
Match loan payments to your income schedule without collateral.
*You will stay on the same site.
Having your documentation ready from the start can compress the review window from days to hours.
This guide shows you exactly which employment records matter most, how lenders verify your information, and the practical steps to prepare your file so the assessment moves forward without delays.
Most personal loan applications require some form of employment confirmation.
Lenders want to know you have a stable income source and that your job situation supports the monthly payment you’re requesting.
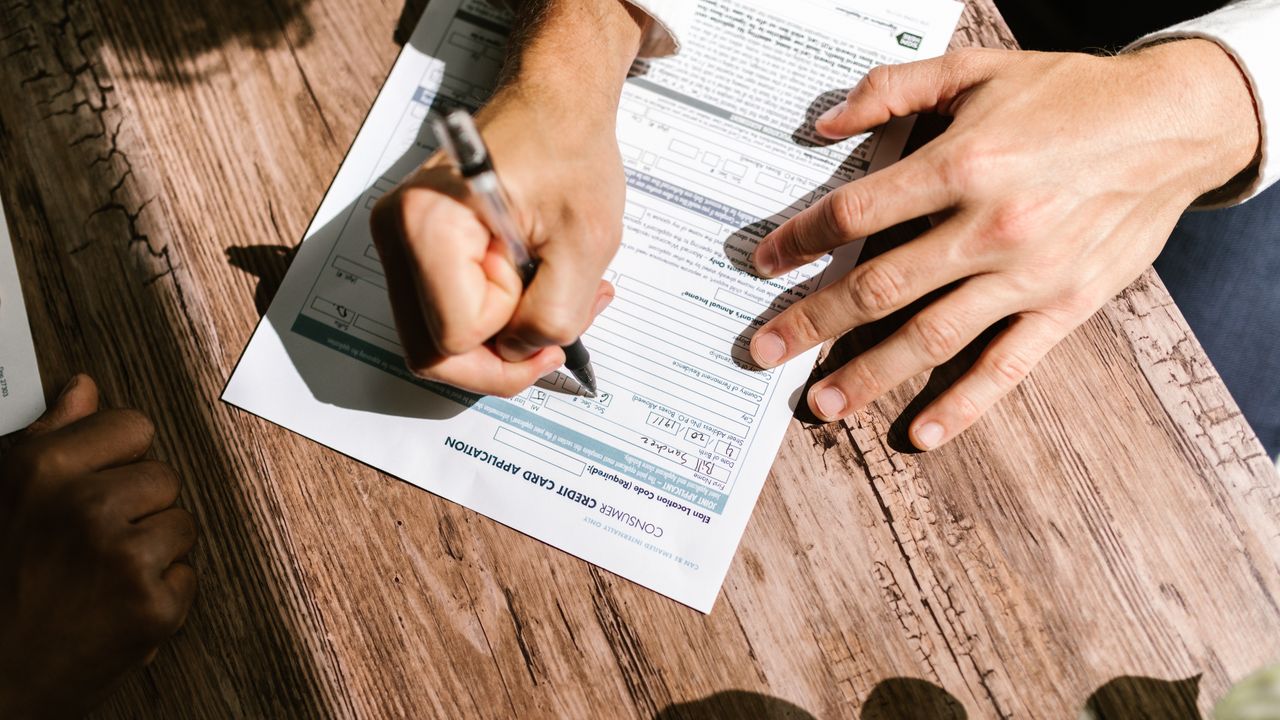
Adapt Your Payments
Flexible Repayment That Fits You
Adjust due dates and amounts to match your income and budget reality.
*You will stay on the same site.
The faster you supply this information accurately, the faster underwriters can make a decision.
Understanding what counts as acceptable verification—and gathering it beforehand—puts you in control of your application timeline.
Why Employment Verification Affects Your Timeline
Personal loan lenders use employment information as a core risk measure. They assess whether your current job will continue and whether your income level justifies the loan amount you need.
If verification takes time—because documents are missing, outdated, or unclear—your application stalls in the queue.
Income verification typically involves confirming your current job title, employer name, start date, and gross monthly or annual income.
CHECK YOUR OPTIONS
Secure Flexible Payments on Personal Loans Up to $20,000
Discover how flexible payment options on personal loans up to $20,000 let you align installments with your income. Learn to verify safe lenders and protect your data during online application.
*You will stay on the same site.
The lender may request recent pay stubs, tax returns, or a verification letter directly from your employer. Each step adds time unless you’ve prepared in advance.
Self-employed borrowers often face longer verification periods because they must provide tax returns spanning multiple years plus business financial statements.
W-2 employees, by contrast, can usually satisfy verification with one or two recent pay stubs and a quick employer phone call.
Understanding where you fit in this spectrum helps you gather the right documents immediately.
State licensing rules also influence how quickly a lender can move. Some lenders operate in limited states, and verification protocols vary by location.
A lender operating nationally must follow each state’s consumer protection rules, which can add procedural steps but also protect you from predatory practices.
Documents That Speed Your Verification Process
Having the correct paperwork ready eliminates back-and-forth requests. Here’s what typically accelerates the employment verification stage:
- Recent pay stubs – Usually the most recent one to two months, showing gross income, deductions, and employer details.
- W-2 or 1099 forms – Tax documents from the prior year or two, especially if you’re applying for a larger loan amount.
- Employer verification letter – A signed note from your HR department confirming your current job title, hire date, and compensation.
- Bank statements – Recent deposits showing income deposits, which corroborate your stated earnings.
- Tax returns – Full personal or business returns, critical if you’re self-employed or earn variable income.
Having these documents ready—either scanned and ready to upload or physically available for overnight courier—means you don’t delay your application while searching for files.
Lenders appreciate when borrowers arrive prepared; it signals reliability and can positively influence underwriter perception.
The Role of Debt-to-Income Assessment
Employment verification feeds directly into your debt-to-income (DTI) ratio, a metric lenders use to decide your loan eligibility and size.
Your verified monthly income is divided by your total monthly debt obligations—credit card payments, car loans, existing personal loans, and mortgage or rent.
If your stated income cannot be verified quickly, the lender may delay calculating your DTI until documentation arrives.
Some lenders will use a conservative estimate based on industry averages, but that estimate may lower your approved loan amount or require additional verification before funding.
Check your eligibility by calculating your own DTI first. Add up your minimum monthly debt payments and divide by your gross monthly income.
Most lenders prefer a DTI below 43 percent, though some may approve up to 50 percent depending on credit score and other factors.
Knowing this ratio before you apply helps you choose a loan amount you’re likely to qualify for, which speeds decision-making.
Soft Inquiry vs. Hard Inquiry in the Verification Timeline
When you start a personal loan application, most lenders perform a soft inquiry to check your credit report and basic employment information.
This inquiry does not affect your credit score and helps the lender offer you a pre-qualification estimate quickly.
Once you formally submit your application, the lender typically moves to a hard inquiry—a full credit report pull that does affect your score slightly. At this stage, they also request your employment verification documents.
The hard inquiry and the document review happen roughly in parallel, so the lender gains a complete picture of your creditworthiness and repayment ability at the same time.
Having your employment documents ready before the lender even requests them can mean the verification portion is complete the same day you apply formally.
This is why many borrowers see approvals within one business day—not because underwriting is instant, but because they came prepared.
Self-Employment and Income Verification
Self-employed applicants and freelancers face longer verification timelines because income is less standardized.
Lenders typically request two years of business or personal tax returns, profit-and-loss statements, and sometimes bank statements showing business deposits.
If you’re self-employed, Submit your application with complete tax documentation attached from day one. Don’t wait for the lender to ask.
Many self-employed borrowers receive pre-qualification offers that specify exactly which documents they need; gathering those documents immediately keeps momentum on your side.
Some lenders specialize in self-employed lending and have streamlined verification processes. Comparing options among lenders experienced with your income type can significantly reduce your assessment timeline.
How Lenders Verify Employment Directly
Beyond reviewing your documents, lenders may contact your employer directly to confirm your employment status and income.
This verification typically takes one to two business days. Most employers have an HR hotline or dedicated verification department that answers these calls quickly.
If you’re between jobs or in a probationary period, employment verification becomes more complex. Some lenders won’t lend to applicants with fewer than six months at their current employer; others will if your overall credit profile is strong.
Being upfront about recent job changes during application—rather than having the lender discover it during verification—can prevent surprises and help underwriters evaluate your stability fairly.
If you know a job change is coming soon, consider applying before the transition if possible, or wait until you’ve been in the new role for at least 30 days and can provide documentation from the new employer.
Accelerating the Assessment with Clear Communication
Increases security and speeds decisions when you respond promptly to any lender requests.
If an underwriter needs clarification on your employment history or questions why you changed jobs, answering the same day—rather than days later—keeps your application moving.
Designate a single email address and phone number for all lender communication, and check them daily during your application period.
Some lenders operate automated callback systems; returning those calls quickly signals that you’re serious about the loan and ready to complete the process.
If you receive a conditional approval—meaning you’re approved pending final employment verification—don’t delay. Get your employer verification letter signed immediately.
The lender may fund your loan the moment all conditions are satisfied, so speed in this final stage directly translates to funds reaching your account sooner.
Comparing Lenders on Verification Speed
Not all personal loan lenders move at the same pace. Some have automated verification systems that check your employment data electronically; others rely on manual review.
Online lenders often move faster than traditional banks because they’ve invested in streamlined verification technology.
When you Compare options today, ask each lender about their average time from application to funding. Many will quote “same-day decisions” for qualified applicants, but that typically means a decision on eligibility—not funds in your account.
Funds usually arrive one to three business days after approval, depending on your bank and whether the lender performs any final verification before disbursement.
Credit unions may offer lower rates but sometimes take longer for verification, especially for non-members or those with limited credit history.
Banks with physical branches may have faster verification if you can walk in with documents; purely online lenders are fast on decisions but slower on fund delivery in some cases.
Preparing Your Application File in Advance
Prepare your application by gathering everything lenders might request before you submit anything. Create a folder—digital or physical—containing:
- Your most recent two months of pay stubs.
- Your most recent W-2 or tax return.
- A government-issued ID (driver’s license or passport).
- Social Security number (you’ll enter this during application).
- Your employer’s name, address, and phone number.
- Your supervisor or HR contact name and title.
- Bank statements showing where your paycheck deposits.
- A brief employment history for the past two years (job titles, employers, dates).
Some lenders offer a checklist during the application process; print or screenshot it and cross off items as you gather them. This removes guesswork and ensures you don’t miss anything.
Red Flags in Verification That Delay Approval
Certain employment situations trigger extended verification.
These include gaps in employment history, frequent job changes (more than one per year), inconsistency between your stated income and what your tax returns show, or employment at a company that’s hard to reach.
If you have gaps, provide a brief written explanation during application—don’t wait for the lender to ask. If you changed jobs recently but stayed in the same field at similar pay, that’s usually easier to explain and verify than a career shift.
If your income varies significantly year to year, be ready to explain why and provide documentation showing the range.
If you work for a small business or startup with a new employer verification line, provide your direct supervisor’s contact information and let them know a lender may call.
This prevents the lender from getting a “no record found” response that could derail your application.
Employment Verification and Credit Score Impact
Your credit score works alongside employment verification. A strong credit score (typically 620 or higher) combined with clear employment verification can lead to approval within one business day.
A weaker credit score (below 580) combined with employment verification that takes time can stretch the timeline to a week or longer.
If your credit score is marginal, having bulletproof employment documentation becomes even more important.
It reassures the lender that even if your credit history shows past difficulties, your current income and job stability justify approval.
Check your credit report for errors before applying. If you spot incorrect employment information or outdated addresses listed under your name, dispute them with Equifax, Experian, or TransUnion before applying for the loan.
Fixing these issues beforehand speeds verification and improves your chances of the best available rates.
What Happens After Verification Approval
Instant credit access does not follow verification approval immediately. Once the lender verifies your employment and confirms your eligibility, you receive an approval decision.
From that point, funds typically arrive within one to three business days through ACH transfer to your bank account.
Some lenders offer next-business-day funding for applicants who apply and complete verification before 5 p.m. on a weekday.
Weekend or holiday applications usually push funding to the following business day. Choose your lender based on their fund disbursement speed if you’re in a genuine time crunch.
After funding, you’ll receive loan documents and payment schedule details. Review these carefully to understand your APR, origination fees (if any), monthly payment amount, loan term, and any prepayment penalties.
Employment verification doesn’t end at funding; lenders sometimes conduct random re-verification during your loan term to ensure you remain employed as stated.
Legitimate Vs. Predatory Verification Practices
Legitimate personal lenders always verify employment through standard practices—document review, employer contact, and credit bureau data.
They do not ask you to pay a fee upfront to “verify” your employment or guarantee approval.
The Federal Trade Commission (FTC) and Consumer Financial Protection Bureau (CFPB) regulate how lenders collect and use employment information.
Predatory lenders sometimes misrepresent verification requirements or use verification as a pretext to request personal financial information they don’t need.
If a lender asks you to deposit money as a “verification fee” before reviewing your application, that’s a red flag.
Legitimate lenders cover verification costs from origination fees (which are disclosed upfront in your Loan Estimate document) or from their own cost of doing business.
State licensing rules vary, but most states require lenders to be licensed and to follow transparent lending practices.
Check your state’s financial regulator website to verify whether a lender holds proper licenses before committing to an application.
Moving Forward With Confidence
Move forward now by taking action on your personal loan application only after you’ve gathered and organized your employment verification documents.
Speed comes from preparation, not from rushing through forms with incomplete information.
Contact lenders that specialize in your situation—whether that’s W-2 employment, self-employment, or recent employment changes.
Ask them directly about their average approval timeline and what documents they need most urgently. Many will give you a clear picture of how long verification typically takes and what you can do to accelerate it.
Review the loan terms carefully before accepting any offer. Employment verification confirms your ability to repay, but your approval amount, APR, and monthly payment depend on your full financial profile.
Understanding these terms helps you make a decision aligned with your budget and financial goals.
Remember that lenders cannot guarantee approval or funding speed; they can only estimate based on historical data and your application completeness.
By preparing your employment documentation thoroughly and choosing a lender known for responsive verification processes, you put yourself in the strongest position for a fast, fair assessment and approval decision.