Complete Your Loan Application Form Correctly First Time
Accurate application forms form the foundation of a smooth personal loan process.
Flexible Repayment Personal Loans Tailored to Your Budget
Discover how flexible personal loans let you align repayments with your income, reduce financial stress, and manage unexpected expenses without rigid payment schedules. Explore your options today.
*You will stay on the same site.
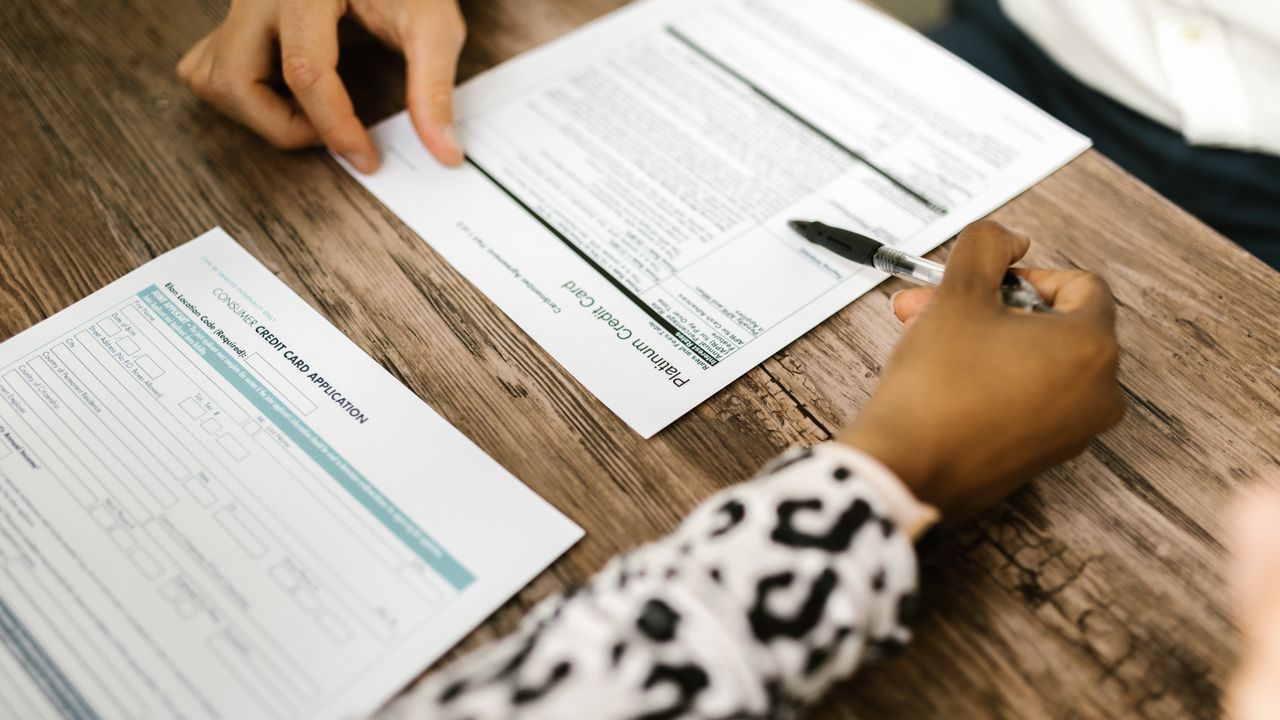
When you take time to complete your loan application correctly the first time, lenders can review your details without requesting clarifications or additional documents, which means you move toward a funding decision faster.
Understanding what goes into each field and why lenders ask for specific information helps you present yourself confidently and avoid delays that could cost you weeks.
Getting a personal loan starts with a straightforward application, but many borrowers rush through and create friction that slows everything down.
Your goal is to provide clear, consistent and verifiable information so the lender’s assessment team can work efficiently.
STREAMLINED PROCESS
Flexible Repayment Options for Personal Loans in Australia
Discover how flexible repayment personal loans let you adjust payments to match your income and budget. Explore manageable terms tailored to your financial situation.
*You will stay on the same site.
This guide walks you through the key sections of a typical personal loan application and shows you how to fill each one so lenders see you as a reliable borrower.
Essential Information Lenders Need
Before you sit down with the application form, gather the documents you will likely need.
Most lenders ask for proof of identity, such as a valid driver’s licence or passport, proof of current address via a recent utility bill or lease agreement, and documentation of your income.
If you are employed, payslips from the last two to three months and a recent tax return help verify your earnings. Self-employed applicants should prepare business tax returns and accounting statements.
Lenders also want to understand your existing debts and financial commitments.
QUICK OPTIONS GUIDE
Flexible Repayment Personal Loans Matching Your Cash Flow
Discover how personalised repayment schedules on personal loans let you align payments with your income and reduce financial stress. Explore loan amounts, terms and real-world applications today.
*You will stay on the same site.
This includes credit card balances, car loans, home loans, and any other regular repayment obligations.
Your credit history matters because it shows how reliably you have managed borrowed money in the past.
When you can check eligibility upfront, you get a realistic sense of whether your application will move forward without surprises.
Income verification is one of the most critical elements because it demonstrates your capacity to repay the loan. Be precise about your gross annual or monthly income depending on what the form requests.
Include all sources such as salary, commissions, bonuses and investment returns if applicable. Lenders cross-check this information against your tax records, so accuracy is essential.
Filling Out Your Loan Application Form Correctly
Start by reading the entire form before writing anything. Many applications ask related questions in different ways to verify consistency, so understanding the full scope helps you answer accurately from the beginning.
Take your time and use black or blue pen if submitting a paper form, writing clearly so no reviewer has to guess what you have written.
When you enter loan amount, match it exactly to what you need. Asking for more than necessary costs you extra interest, while asking for too little means you will need to reapply later.
Be specific about your purpose—whether it is debt consolidation, home improvement, car purchase, medical bills or another expense.
Lenders assess risk differently depending on the use, and stating it clearly helps them apply the right criteria.
For the loan term section, select term that balances affordable monthly payments with total cost.
A shorter term means you pay less interest overall but larger monthly payments, while a longer term spreads payments out but increases total interest paid.
Think about your budget realistically before committing to a term length. Many borrowers choose terms between one and seven years depending on the loan size and their income stability.
Personal details must match your official documents exactly.
If your payslips show your name as John Robert Smith, do not write John R Smith or John Smith on the application.
Inconsistencies can trigger verification delays or even application rejection because lenders cannot confirm your identity with certainty.
Double-check your phone number and email address so the lender can contact you quickly if they need clarification.
Employment information should include your current job title, employer name, start date, and salary. If you have changed jobs recently, include your previous employer details and dates of employment.
Lenders want to see employment stability, so gaps or frequent job changes may raise questions. Be honest about your employment status; if you are on a fixed-term contract, probation, or casual hours, state this clearly.
Building a Stronger Application
Your debt-to-income ratio matters significantly to lenders. This is calculated by dividing your total monthly debt repayments by your gross monthly income.
If you earn $4,000 monthly and currently pay $800 in loans and credit cards, your ratio is 20 per cent, which is generally healthy.
Most lenders prefer to see ratios below 40 per cent, though this varies by lender and loan size. Knowing your ratio before applying helps you understand whether you are in a strong position.
Address information needs to be current and verifiable.
If you have moved recently, provide both your old and new addresses with the dates you lived at each location.
Lenders verify this information and want to see stability. Renters should provide their landlord or property manager details if requested, while homeowners can reference their mortgage documents.
When listing financial commitments, include everything: credit cards even if the balance is zero, car loans, personal loans, student loans, and any regular payment obligations.
Do not try to hide debts because lenders will discover them through your credit report anyway, and omitting them signals dishonesty.
A complete and transparent picture actually works in your favour because it shows you understand your financial situation fully.
Review payment estimate information provided by the lender carefully.
If they give you an estimated monthly payment, interest rate, and total cost of the loan, make sure these figures align with your expectations and budget. Ask questions if anything seems unclear.
Responsible lenders will explain establishment fees, comparison rates, and early repayment options.
Comparison rate includes the interest rate plus certain fees and shows you the true cost of borrowing, making it easier to compare offers fairly.
Some lenders offer a pre-qualification process where you provide basic information and they assess whether you are likely to qualify.
This may involve a soft credit inquiry that does not affect your credit score, giving you a sense of eligibility before submitting a full application.
This step can save time if it turns out you do not meet the lender’s minimum requirements.
Authorisation and consent sections require your careful attention.
You will be asked to allow the lender to obtain your credit report, verify your income and employment, and in some cases contact your employer or financial institution.
You might also authorise automatic payment from your bank account once approved.
Read these sections thoroughly and only tick boxes you are comfortable with, though refusing standard verifications will likely result in application rejection.
Sign and date your application as required, and keep a copy for your records. If applying online, take screenshots of your completed form before submission.
If the lender asks you to submit documents, check their requirements for format, size and quality. Blurry or partially cut-off documents slow down the verification process.
After submission, note the application reference number and any expected timeframe for a decision. Different lenders have different processing speeds depending on their systems and team capacity.
If approved, depending on the lender and your bank’s processing schedule, funds may be available within one to five business days after you sign the .
Responsible lenders will inform you of any ongoing obligations, such as interest rate changes, early repayment fees, or account maintenance requirements.
Taking these steps means your application presents you in the strongest possible light and allows the lender’s team to work efficiently toward a decision.
An application filled out with care, accuracy and honesty demonstrates that you take your financial commitments seriously and understand what you are agreeing to.
This approach builds confidence and moves you toward approval without unnecessary back-and-forth, saving everyone time and keeping you on track to access the funds you need.